

Robinhood Banking
by Robinhood
4.9
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.9
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
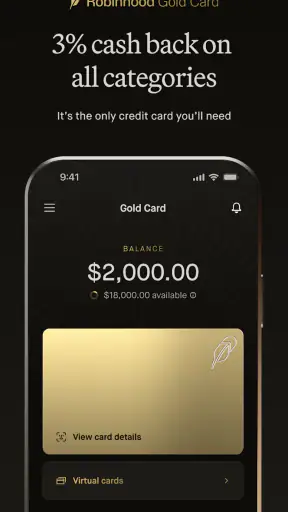
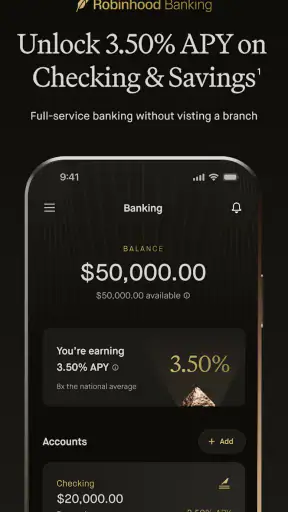
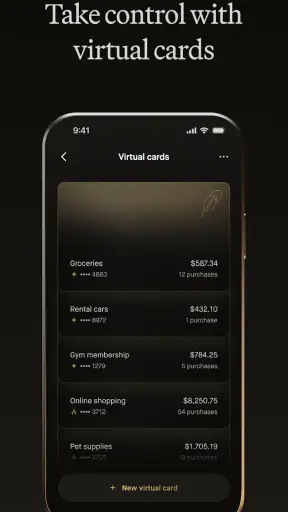
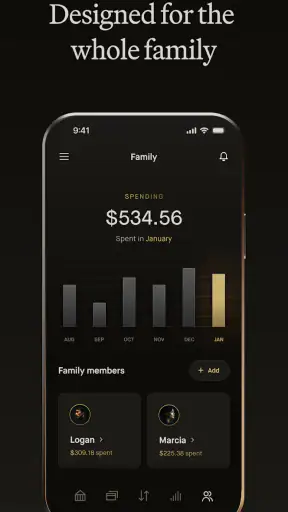
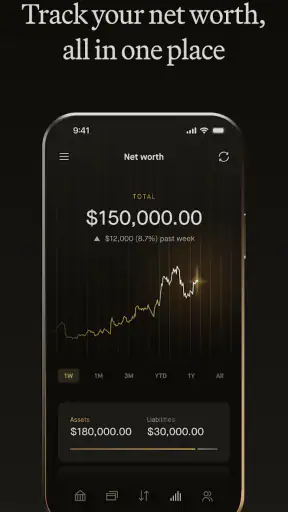
 Analysis by Getfullapps
I approached Robinhood Banking as a finance app that needs to do more than display balances. A banking tool is something I may open while commuting, in bright sunlight, with one hand occupied, or when I am already stressed about a payment. That makes readability, navigation, and recovery from mistakes just as important as the account information itself. In my experience, this app is most interesting for people who want banking and Robinhood’s financial environment in one place, but it is not automatically the best fit for every banking routine.
Robinhood, the developer behind it, presents the app as a free banking product for everyone, with a minimum operating-system requirement of Android 7.0 or newer. It was released on March 19, 2024, and the current version is 2.18.7. The store summary describes it as “Credit Card & Banking,” while the shorter description calls it “Robinhood Banking.” Those labels give a useful first impression, but they do not explain how comfortable the app is for different users. That is where day-to-day use matters more than the headline.
How Robinhood Banking feels to use in different situations
I find that Robinhood Banking’s mobile format matters most when the situation changes: a quick check between errands calls for a different pace than investigating an unfamiliar transaction at home. I’ll look at how those everyday contexts affect confidence and decision-making, then consider which users are most likely to benefit from that flexibility.
Readability and navigation are strongest when you want a quick answer
The main strength I noticed is the app’s suitability for short financial checks. When I want to know whether money has arrived, whether a purchase has cleared, or whether my available balance looks right, a focused banking interface is more useful than a crowded desktop-style dashboard. The best mobile finance experiences let me answer one question quickly and leave, and Robinhood Banking generally fits that pattern.
That simplicity can help people who find complex financial software tiring. A user does not necessarily want to work through several layers of menus just to confirm a transaction. Clear grouping of banking tasks, account information, and card-related activity makes a real difference for anyone who is new to digital banking or who prefers a limited number of choices on screen.
At the same time, a streamlined layout can become less comfortable when I need to investigate something. Quick access is not the same as deep explanation. If a transaction needs closer inspection, I want the path from the balance to the individual activity and then to the relevant support information to feel obvious. A finance app should never make me guess whether a number is pending, completed, available, or merely displayed as part of a broader total.
My practical advice is to spend a few minutes exploring the account and activity areas before relying on the app for an urgent task. Open a recent transaction, look for the available actions, and learn where account help is located. This small preparation is especially useful for users with memory difficulties or anyone who becomes uncomfortable when an interface changes between visits.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Text hierarchy also matters. Financial apps often place a large balance beside smaller labels and secondary figures. That can be efficient for experienced users, but it may be confusing for someone with low vision, dyslexia, or limited familiarity with banking terminology. I found that the app is easiest to understand when I slow down and read the labels rather than treating every prominent number as spendable money.
The most important accessibility habit is to verify what each balance represents before making a decision. A quick glance is convenient, but it should not replace checking transaction status or the meaning of an amount when the difference could affect a bill or purchase.
Motor and sensory considerations depend on the phone, not just the app
Robinhood Banking is designed for touch interaction, which makes it approachable for many people who prefer tapping to navigating a traditional website. The phone format can also be easier than a large banking portal for users with limited stamina, because a short session can be completed while seated or away from a desk. For someone managing finances between other tasks, that flexibility is valuable.
One-handed use is a realistic test. I may be holding a bag, standing on a train, or using the phone with my non-dominant hand. In those moments, small controls, closely placed actions, or an unexpected screen transition can create friction. I recommend avoiding important transfers or account changes while distracted. For routine balance checks, the mobile format works well; for decisions involving several confirmation steps, I prefer a stable position and more time.
People with tremors or reduced precision should pay attention to confirmation screens. A finance app should be treated differently from a social app: an accidental tap can have consequences. I would use deliberate pauses, enlarge the phone’s system text if needed, and review the final screen before confirming an action. Those are general device settings and habits rather than special Robinhood guarantees, but they make this type of app safer to handle.
Sensory context changes the experience considerably. In a quiet room, a compact banking screen can feel calm. In glare, darkness, a noisy station, or a moving vehicle, the same screen may be harder to interpret. This is one reason I would not judge the app only by how it feels at home. A user with light sensitivity may prefer a darker environment; someone with hearing loss should not depend on sound alone to understand whether an action succeeded. Visual confirmation and readable status text are more dependable.
Users who rely on screen readers or magnification should test the tasks that matter most to them before moving their everyday banking routine into the app. I would specifically check whether account labels, transaction descriptions, buttons, and confirmation messages are announced in a sensible order. I cannot treat a modern interface as proof of complete assistive-technology support. The responsible approach is to test the actual phone, operating-system settings, and workflows together.
Situational access is where a mobile bank earns its place
The strongest use case is a quick check during an ordinary day. Imagine I am at a supermarket and want to confirm that a payment has not pushed my available money below the amount needed for a later bill. I can open the banking app, inspect the relevant activity, and make a more informed choice before reaching the checkout. That is a modest task, but it is exactly the kind of moment when a phone-based bank can be more useful than waiting until I get home to use a computer.
Another useful situation is travel within my normal routine. A mobile account gives me a way to review activity without carrying paper records or opening a full browser session. However, I would not interpret mobile access as independence from connectivity, battery life, or the phone itself. If my device is nearly empty, locked away, damaged, or unavailable, the convenience disappears. A sensible backup plan still matters for anyone who depends heavily on digital banking.
The app may also suit people who want their financial life to feel less fragmented. Instead of checking one service for card activity and another for a broader view of their money, some users may prefer Robinhood’s ecosystem. That convenience is personal: if I already use Robinhood and value keeping related financial activity together, the app has a clear appeal. If I want a traditional bank with extensive branch support, household account tools, or a long-established set of service channels, a conventional banking provider may feel more reassuring.
For people with variable attention or executive-function challenges, the ability to complete a small task quickly can reduce avoidance. I can check activity, notice an unfamiliar purchase, and decide what to do next without opening a laptop. The trade-off is that a compact interface may encourage me to act too quickly. I would use it for monitoring and straightforward actions, but I would reserve complicated financial planning for a calmer session with notes in front of me.
Older phones deserve special consideration. The app supports Android versions beginning with 7.0, which makes it available to users who have not moved to a recent device. Yet operating-system eligibility is not the same as a smooth experience on every older handset. Screen size, performance, display quality, and system accessibility settings can all affect comfort. Before making it the center of a banking routine, I would test login, balance viewing, transaction review, and any action I expect to use regularly.
Where the experience still creates barriers
The first barrier is financial language. Even when navigation is simple, terms such as available balance, pending activity, credit, and completed payment can be easy to confuse. This is not unique to Robinhood Banking, but it matters because a clean interface can make complex concepts appear simpler than they are. I would like every important figure to be paired with plain context, especially for users who are learning how banking works.
The second barrier is the gap between convenience and reassurance. A mobile-first service can be excellent for quick access, but some people need a human explanation when something goes wrong. If a user has difficulty reading small text, using a touch screen, remembering steps, or communicating through digital forms, support access becomes part of accessibility. I would not choose this app solely because it is easy to open; I would also consider how comfortable I am resolving an unfamiliar problem through the available in-app route.
Security steps can introduce another layer of difficulty. Strong account protection is important, but repeated authentication, device changes, or recovery tasks can be challenging for people with memory impairments, limited dexterity, or inconsistent access to their usual phone. I recommend keeping recovery information organized in a secure place and avoiding account changes during a rushed moment. The safest workflow is one that I can repeat calmly and understand, not merely one that works once.
There is also a cognitive trade-off in combining banking with a broader financial brand. For some users, one familiar environment reduces switching. For others, it may blur the difference between everyday spending money and longer-term financial activity. I would keep a clear personal distinction between money needed for bills and money I am willing to use elsewhere. The app can present information, but it cannot make that decision for me.
People who need highly specialized accessibility support should be cautious about assuming that a popular rating reflects their own experience. Robinhood Banking has an average rating of 4.9 from around 25 thousand ratings, with roughly 2.3 thousand written reviews, and it has passed 100 thousand installs. Those figures suggest strong general reception, but they cannot tell me whether the app works well with my screen reader, magnification level, motor settings, language preferences, or particular banking habits.
Who should use it, and who should choose another route?
I see Robinhood Banking as a good option for someone who wants a free finance app with a modern mobile workflow, already feels comfortable managing money from a phone, and values the connection to Robinhood. It is especially appealing for quick balance checks, reviewing card activity, and handling routine banking away from a computer. The Everyone age rating also makes its intended audience broad, although younger or inexperienced users still need a clear understanding of financial terms before acting.
I would be more hesitant to recommend it as the only banking solution for someone who depends on branch visits, prefers extensive desktop tools, needs a very specific assistive-technology workflow, or wants personal guidance for complicated financial decisions. A traditional bank may be better when physical access, established service routines, or a wider range of account-management options matters more than mobile simplicity.
Compared with keeping a separate banking app and using Robinhood independently, this product can reduce app switching. Compared with a conventional bank’s mobile application, its appeal is likely to be the Robinhood-centered experience rather than a universal solution for every household. The right comparison is not simply which interface looks cleaner. I would compare how quickly I can identify a transaction, how confidently I can understand balances, how accessible the support path feels, and how well the service fits the rest of my financial life.
Before committing, I would run a small trial: sign in at home, inspect the balance labels, review a normal transaction, adjust the phone’s text or display settings, and repeat the same tasks in a less comfortable environment. I would also ask myself whether I can complete those steps without rushing. This test reveals more about inclusive usability than a rating alone.
My inclusive verdict
Robinhood Banking succeeds when I treat it as a focused mobile banking tool rather than a complete answer to every financial need. Its free price, broad age classification, current version 2.18.7, and compatibility with Android 7.0 or newer make it approachable for a wide range of phone users. The positive reception is encouraging, but accessibility is personal, and a high average rating cannot replace testing the workflows that matter to me.
I like it most for quick, purposeful checks: confirming activity, understanding what is happening in an account, and staying connected to banking while away from a desk. I am less comfortable recommending it blindly to people who need guaranteed compatibility with a particular assistive setup or who want a traditional, human-led banking experience. The app’s convenience is real, but convenience should be measured by whether I can use it accurately and confidently, not merely by how fast it opens.
My final recommendation is to try it with low-risk, familiar tasks first. Increase system text size if reading is tiring, use a quiet and stable setting for important actions, review confirmation details carefully, and keep a backup way to manage urgent finances. If those steps feel natural and the Robinhood ecosystem matches your needs, this can be a practical everyday banking companion. If they feel like work, a different banking option with stronger personal support or a more comfortable accessibility fit will be the better choice.
Pros
- Commission-free stock, ETF, and options trading is easy to access.
- The clean interface makes portfolio tracking simple for beginners.
- Recurring investments can help users build consistent saving habits.
- Instant deposits may provide quicker access to available funds.
- Fractional shares let users invest with smaller amounts of money.
Cons
- Investment products and account features vary by country and eligibility.
- Options and margin trading can expose inexperienced users to significant losses.
- Customer support is mainly digital, with limited phone assistance.
- Cash interest rates and benefits may change over time.
- The app offers fewer advanced research tools than some full-service brokers.
FAQs for Robinhood Banking
What is Robinhood Banking, and what services does it offer?
Robinhood Banking is the cash-management and spending side of the Robinhood financial platform, designed to let eligible customers manage money alongside their investing account. Depending on availability and account eligibility, users may receive a spending account, a debit card, direct deposit options, bill-payment features, transfers, and access to uninvested cash programs. Available services, limits, and protections can vary by location and may change over time.
Is my money in Robinhood Banking insured and protected?
Protection depends on which Robinhood product holds your money. Eligible uninvested cash may receive FDIC insurance through a sweep program involving participating banks, subject to applicable limits and conditions. Securities accounts are generally protected by SIPC rather than FDIC insurance. Users should read the current agreements carefully, because insurance does not protect against investment losses, market declines, fraud caused by user actions, or every type of account loss.
Are there fees for using Robinhood Banking?
Robinhood Banking may advertise no recurring maintenance fee for certain standard services, but that does not mean every transaction is free. Possible costs can include out-of-network ATM fees, expedited transfers, card-related services, foreign transactions, margin-related charges, or fees imposed by another bank or payment provider. Before downloading or moving money, review the latest fee schedule and account terms that apply to your specific account.
Can I use Robinhood Banking for direct deposit, bill payments, and everyday spending?
Eligible customers can generally use Robinhood’s spending features for everyday purchases, receive qualifying direct deposits, transfer money, and manage certain bills through the app. The debit card can be used wherever its payment network is accepted, although merchant acceptance and transaction limits may vary. Direct deposits and transfers may also require identity verification, account eligibility, and additional processing time, so the service may not replace every traditional bank function.
What should I know about account eligibility, withdrawals, and customer support?
Robinhood Banking availability depends on factors such as your country or state, age, identity verification, account status, and regulatory requirements. Withdrawals and transfers may be subject to limits, review periods, settlement rules, or temporary holds, particularly after a deposit or account change. Customer support is primarily provided through the app and online help resources, so users who require extensive branch access or immediate telephone assistance should consider that limitation.











